Personal
Boats, RVs, motorcycles, classic cars, and more
The toys deserve real coverage, too. Standard auto and home policies leave big gaps for anything with a motor, a hull, or an agreed value.
What it covers
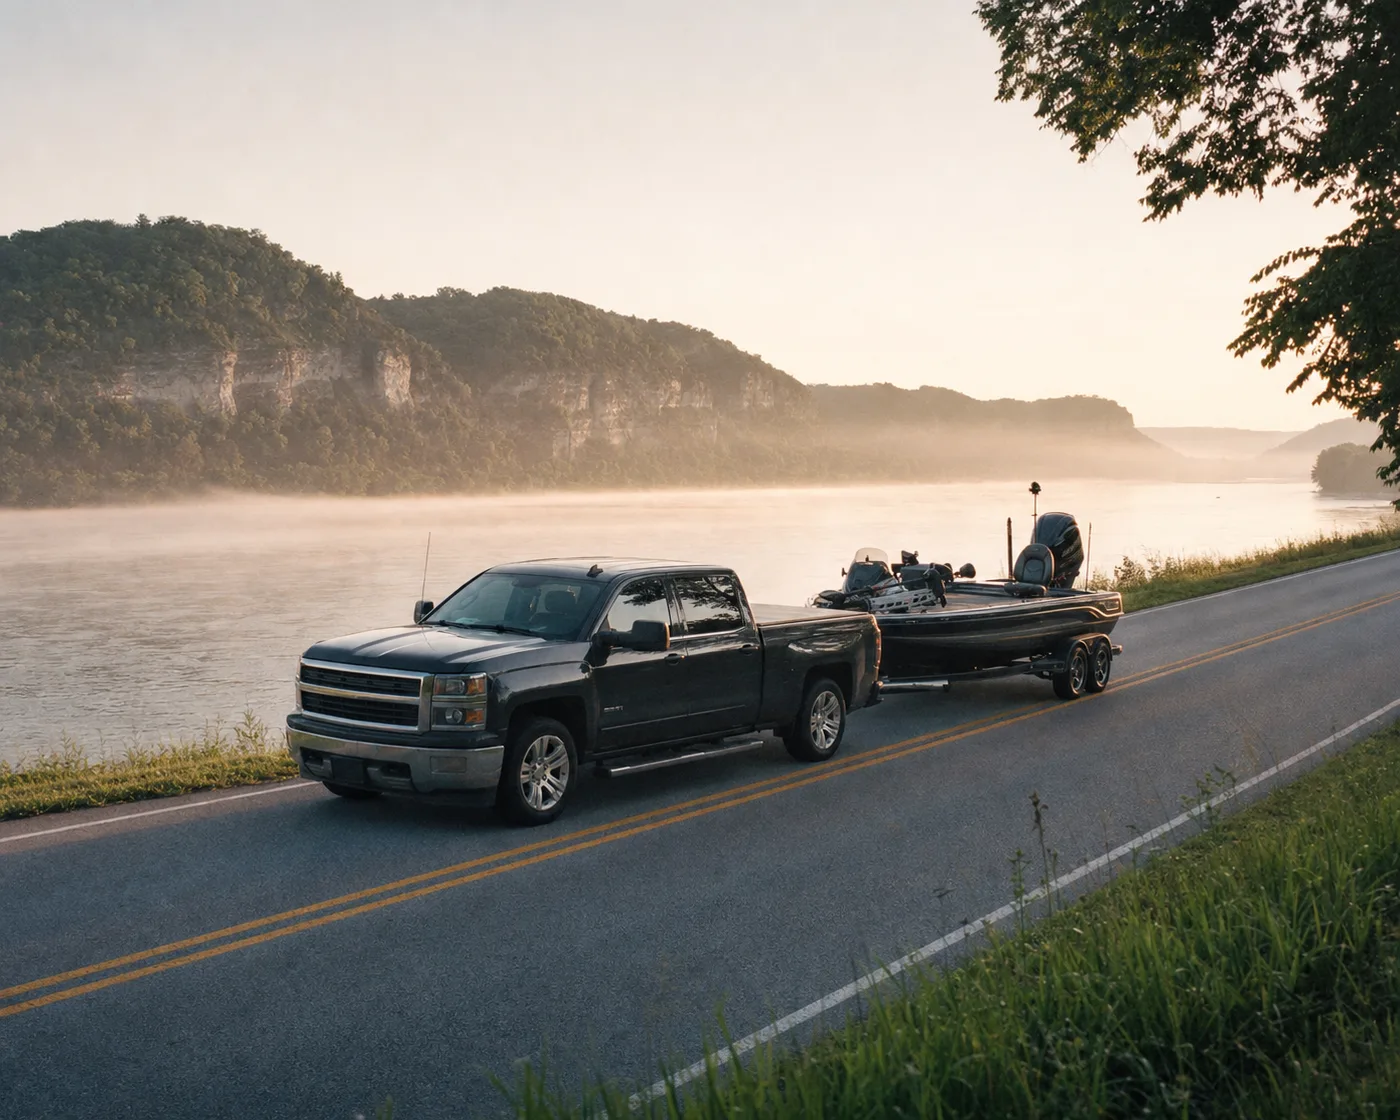
Specialty policies are built for the thing they cover. A boat policy handles liability on the water, physical damage to the hull and motor, the trailer, and the gear on board. RV and camper coverage can include the contents and the cost of a place to stay if the rig is out of commission on a trip. Motorcycle and ATV policies cover accessories and custom parts. Classic and collector cars are written on an agreed value, so a total loss pays the number you and the carrier settled on, not a depreciated book figure. Through carriers like Progressive, Foremost, and American Modern we write the whole garage, and the hangar too.
- Motorcycles and scooters
- Boats and personal watercraft
- RVs, campers, and travel trailers
- ATVs, UTVs, golf carts, and snowmobiles
- Classic and collector cars and trucks
- Airplanes
Who it's for
People who spend summer weekends on the Mississippi and winter weekends on the trails, retirees taking the camper south, and anyone with a restored car in the garage that a standard auto policy would badly undervalue. If it has a motor, a hull, or an agreed value, it belongs on its own policy.
Why quote it with an independent agent
A homeowners policy gives very limited coverage for watercraft and almost none for anything with an engine that leaves the property, so the gap is real. We place each item with the carrier that writes it best and look for the multi-policy discounts that come from keeping the cars, the house, and the toys under one agent.
Good to know
Seasonal use is built into these policies. Boats, motorcycles, and snowmobiles are usually rated for the months they are actually on the water or the trail, and many carriers offer lay-up credits for the storage season. Trailers are not automatically covered by the policy on the thing they carry, so ask for the trailer to be listed. Motorcycles on public roads need liability coverage the same as a car; Iowa and Illinois do not require insurance on a boat, but marinas and lenders usually do.
For classic and collector vehicles, the agreed value is the whole point. You and the carrier settle on the car's worth up front, often with an appraisal or photographs, and that is the number paid after a total loss, with no depreciation argument. Most classic policies also expect limited pleasure use and secure storage, both of which keep the premium low.
What to bring for a quote
- Year, make, model, and the hull or vehicle identification number for each unit
- Where it is stored and how it is used, including approximate hours or miles per year
- Engine size or horsepower
- For classics, an appraisal or your target agreed value
- For aircraft, the tail number and pilot hours
Start online and we will follow up for anything we still need. Start a specialty quote, or call (563) 242-4000.
Looking for a quote instead?
Our three-step quote form takes about two minutes and goes straight to a licensed agent.